A burst pipe does not wait for a convenient time. Neither does a kitchen fire, a wind-damaged roof, or a break-in at your business. In the first hours after a loss, knowing how to file a property claim can help you protect people, limit further damage, and give your insurer the information needed to evaluate what happened.
The goal is not to become an insurance expert while dealing with a stressful event. It is to take calm, practical actions in the right order. Your policy, the cause of loss, your deductible, and state-specific rules all affect the outcome, but a well-documented claim gives you a stronger starting point.
Start With Safety and Prevent Further Damage
Before taking photos or calling anyone, make sure the property is safe. Leave the building and contact emergency services if there is a fire, gas odor, structural concern, active electrical hazard, or criminal activity. For a business, do not send employees back into a damaged space until it is safe to do so.
Once the immediate danger has passed, take reasonable steps to prevent additional damage. That may mean shutting off the main water supply after a plumbing break, placing a tarp over a storm-damaged roof, boarding a broken window, or moving undamaged belongings away from water. Keep receipts for emergency materials, temporary repairs, and necessary protective services.
There is a line to respect here. Do not make permanent repairs or throw away damaged property before the insurer has had an opportunity to inspect it, unless doing so is necessary for health and safety. If an item must be discarded, photograph it from several angles first and keep any identifying labels, serial numbers, or damaged pieces when practical.
How to File a Property Claim Step by Step
Notify the insurer or your agent promptly
Contact your insurance company as soon as you reasonably can. You can also contact your independent insurance agent for guidance on where to report the loss and what information to have ready. A prompt report helps start the claims process and reduces questions about whether damage became worse because it was left unaddressed.
Be prepared to provide your policy number, the property address, the date and approximate time of the incident, a brief description of what occurred, and a phone number where you can be reached. If you do not yet know the full extent of the damage, say so. It is better to give clear facts than to guess.
After reporting, write down the claim number, the name and contact information of the claims representative, and the date and time of each conversation. This simple record can be invaluable if several people become involved in the claim.
Document the damage before cleanup begins
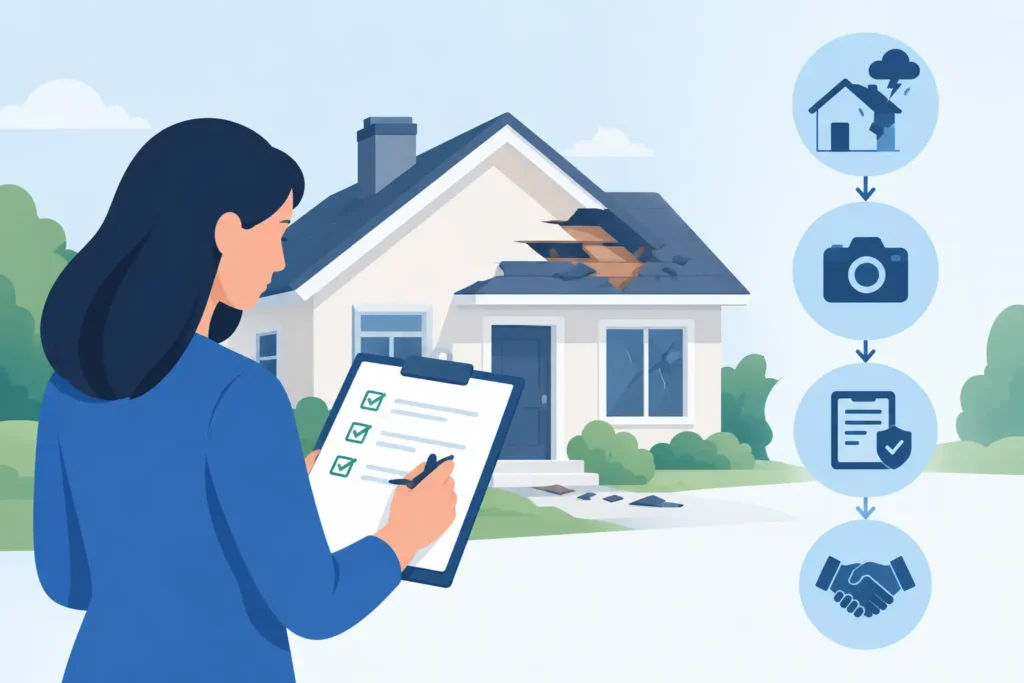
Photos and video create a record that is hard to recreate later. Walk through the property methodically. Capture wide shots that show the location of the damage, then closer images of affected rooms, building materials, furniture, equipment, inventory, and personal belongings.
For a homeowners claim, include items such as flooring, cabinets, appliances, electronics, and clothing. For a commercial property claim, document stock, tools, machinery, tenant improvements, office equipment, and any damage that is affecting operations. Video can be especially useful for showing the scope of water spread, roof openings, or debris across a larger space.
Create a written inventory as you go. Include the item, approximate age, original cost if known, model or serial number, and a short description of the condition. Do not worry if you cannot identify every detail immediately. Start with the highest-value and most clearly damaged property, then add to the list as you locate receipts, invoices, photos, or purchase records.
Preserve evidence of the cause of loss
Your insurer will need to understand not only what was damaged, but why. Keep relevant evidence whenever it is safe to do so. For example, retain a failed hose from a washing machine, photos of a fallen tree, video of a roof leak during a storm, or the police report number after a theft.
If the fire department, police, utility company, or a restoration contractor responds, ask for any reports or reference numbers that may be available. A contractor can help stabilize the property, but be cautious about signing broad repair agreements before you understand the scope of work, cost, and your insurer’s inspection process.
Meet the adjuster prepared, not pressured
The insurer may assign an adjuster to inspect the loss, either in person or remotely. Have your photos, inventory, receipts, emergency repair invoices, and notes available. Walk through the affected areas and point out damage that may not be obvious, such as wet baseboards, damaged contents in storage, or business equipment exposed to smoke.
Ask what happens next, what documents are still needed, and whether the adjuster expects additional inspections. If you receive an estimate, review it carefully. It may be an initial estimate rather than the final amount needed for repairs. If newly discovered damage appears during demolition or repair work, report it promptly rather than assuming it is automatically included.
Understand What Your Policy May Pay For
A property claim is not always a single payment for everything that was damaged. Coverage depends on the policy language, endorsements, exclusions, limits, deductible, and cause of loss. A homeowners policy may address the dwelling, other structures, personal property, and additional living expenses. A commercial property policy may address the building, business personal property, equipment, and, when purchased, certain income losses after a covered event.
The deductible is the amount you are responsible for before covered insurance payments apply. In some areas and policies, wind, hurricane, or named-storm losses may have a separate deductible. That can make a meaningful difference after severe weather, particularly for property owners in New Jersey, New York, and Florida.
Replacement cost and actual cash value also matter. Replacement cost coverage generally considers the cost to repair or replace covered property without deducting for depreciation, subject to policy terms. Actual cash value typically factors in depreciation. Some policies pay an initial amount first and release additional eligible replacement-cost funds after repairs are completed and documented.
Do not assume a loss is not worth reporting because you are uncertain about coverage. A conversation with your insurer or agent can clarify the next step. At the same time, reporting a claim is a decision that should be made thoughtfully when the damage appears close to your deductible or falls outside the policy’s covered causes of loss.
Keep Your Claim Organized From First Call to Final Repair
Claims can move quickly at the beginning and then become more document-heavy as repairs are scoped. Use one folder, paper or digital, for claim correspondence, estimates, invoices, photos, and notes. Save emails and take a few minutes after each call to record what was discussed and any promised follow-up date.
If you need temporary housing because your home is unlivable, ask about additional living expense coverage before making long-term arrangements. Keep receipts for eligible increased costs, such as temporary lodging or additional commuting expenses. For a business interruption, maintain records of canceled orders, reduced sales, payroll, continuing expenses, and steps taken to operate from another location. Business income coverage can be complex, so timely records matter.
Be responsive when the insurer requests documents, but do not feel pressured to sign forms you do not understand. Ask what a document means and retain a copy of everything you submit. If repair costs change, provide the new estimate and explanation in writing.
Common Mistakes That Can Complicate a Claim
Most claim problems do not come from a lack of effort. They come from understandable actions taken under pressure. Avoid these common missteps:
- Waiting too long to report damage or allowing a small problem to become a larger one.
- Cleaning up or disposing of damaged property before it is documented.
- Accepting the first repair estimate without reviewing whether it addresses all visible damage.
- Relying only on phone conversations instead of keeping receipts, photos, and written notes.
- Confusing a contractor’s opinion with a coverage decision under the insurance policy.
You can hire a contractor to provide a repair estimate, and in some situations a public adjuster or other professional may be considered. Whether that is appropriate depends on the size and complexity of the claim. Start by understanding your policy, the insurer’s position, and the documentation supporting your loss.
Let Clear Communication Protect Your Next Step
A property claim is rarely just about repairing a wall, replacing inventory, or drying a floor. It is about restoring a home, a workplace, and a sense of stability. NewEdge Insurance Agency helps clients approach the process with plain-English guidance and personal support when a loss disrupts daily life.
If you have a claim in progress, keep asking clear questions, keep your records together, and make decisions based on the facts of your policy and your property. A steady, well-documented approach gives you the best chance to move from disruption toward repair with confidence.